Security Needs Accountability: Lessons from NATO’s International Audit Community
By Sébastien Lepers, Chair, International Board of Auditors for NATO (IBAN)
The International Board of Auditors for NATO (IBAN)
In a changing security environment, defence expenditure is increasing, programmes are becoming more complex and public expectations for transparency are growing. For Supreme Audit Institutions (SAIs), this raises a fundamental question: how can public audit contribute to accountability and trust when the resources being audited are increasingly linked to national and collective security?
The experience of IBAN is particularly relevant in answering this question.
Established in 1953, four years after NATO’s founding, IBAN is NATO’s independent external audit body. Its mandate is to provide assurance to the North Atlantic Council and the governments of NATO member countries that common funds have been properly used for authorised expenditure. IBAN’s distinctive institutional model is composed of six members appointed by the North Atlantic Council for four-year, non-renewable terms. Its members have independent status and report only to the Council. This independence is essential: IBAN’s role is not to defend or promote particular programmes, policies or institutions, but to provide independent professional assurance based on audit evidence.
IBAN’s work covers three complementary dimensions:
- financial audit, examining NATO bodies and reporting entities;
- performance audit, assessing the economy, efficiency and effectiveness of NATO activities, programmes and operations; and
- NATO Security Investment Programme (NSIP) audit, covering expenditure incurred in the implementation of NATO security investment projects.
Together, these activities provide an important accountability mechanism for resources that are financed collectively by NATO member countries.
This is also what makes the relationship between IBAN and the wider public sector audit and INTOSAI community so valuable. NATO’s audit environment is international by nature, but its professional challenges are shared far beyond the Alliance.
The “Transparency and Accountability in Defence Spending” International Conference
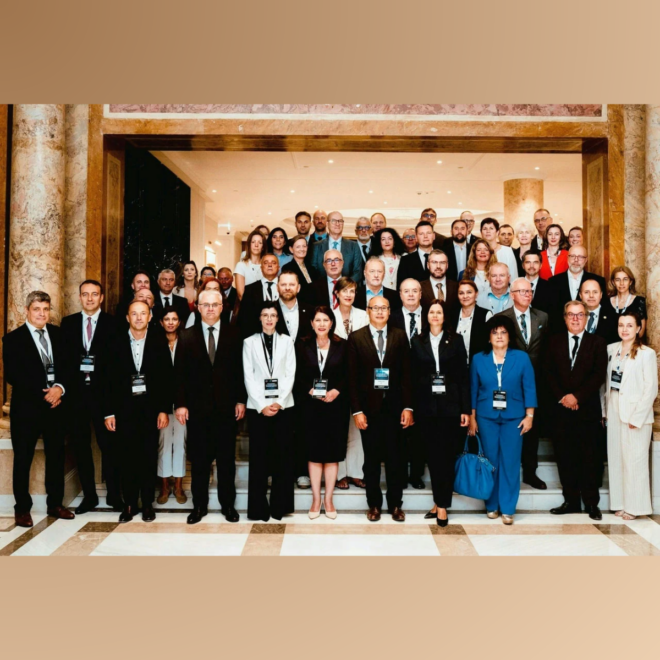
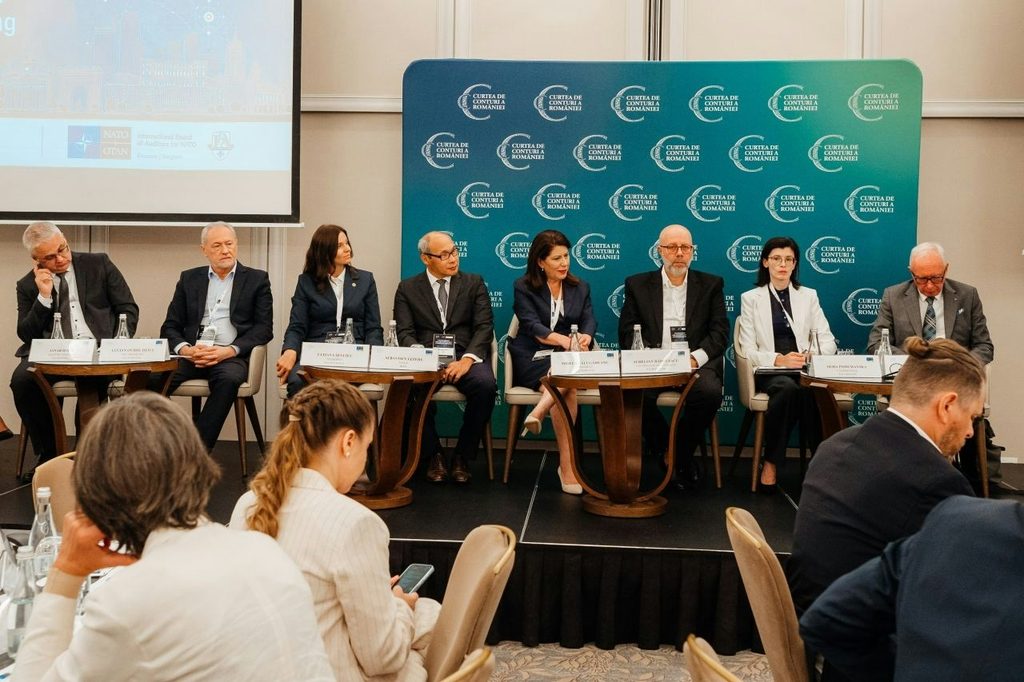
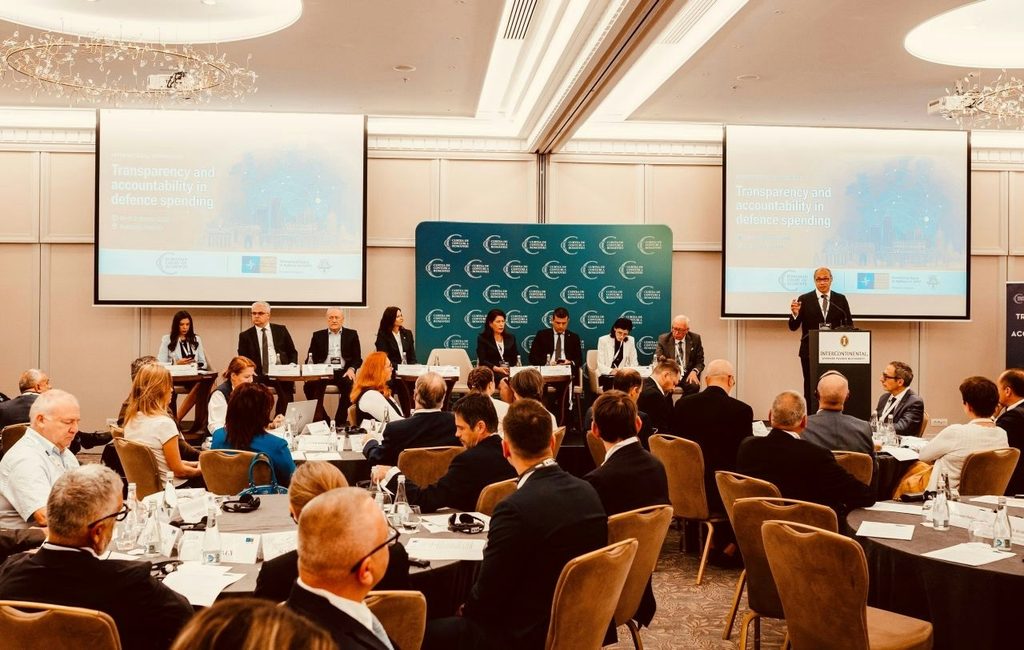
On 10–11 September 2026, the International Board of Auditors for NATO (IBAN) and the Romanian Court of Accounts jointly organized the international conference on “Transparency and Accountability in Defence Spending”.
The conference brought together representatives of SAIs, international audit institutions and defence audit communities from 17 countries, creating a unique forum for professional exchange on the audit of defence expenditure, NATO common funds and security-related programmes.
The discussions highlighted the essential contribution of independent external audit to sound public governance and to maintaining confidence in the use of public resources, while recognising the legitimate requirements of confidentiality associated with defence and security.
The conference also addressed the evolving role of auditors in an increasingly complex defence environment. Major investment programmes, rapidly developing technologies, changing procurement models and new security requirements are creating new challenges for audit institutions. Auditors must therefore continue to adapt their methodologies, develop specialised expertise and strengthen their ability to assess not only compliance, but also economy, efficiency and effectiveness.
Defence Auditing: Transparency Without Compromising Security
A central theme throughout the Bucharest conference addressed one of the most difficult questions facing public auditors today: how to strike an appropriate balance between transparency with the legitimate protection of sensitive information in the defense sector.
Defence is different from many other areas of public expenditure. Information concerning capabilities, military operations, infrastructure, procurement or strategic programmes may legitimately require protection.
But confidentiality and accountability are not opposites. While the nature of many defence activities may restrict the disclosure of certain information, this should not weaken the principles of accountability, independent oversight and sound financial management.
The challenge for auditors is therefore not to seek unrestricted disclosure. It is to ensure that appropriate mechanisms of independent oversight remain effective even when information cannot be made public. This requires professional judgement, robust audit methodologies, appropriate access to information, secure working arrangements and clear reporting frameworks.
Participants engaged in discussions about how to ensure meaningful accountability within the boundaries imposed by security requirements.
That distinction is particularly important at a time when defence expenditure is increasing across the Euro-Atlantic area. The greater the resources committed to collective security, the greater the importance of sound financial management, effective controls and independent assurance.The Alliance is accountable to its member governments and their taxpayers for the financial resources provided to it.
The Value of an International Audit Community
One of the most important messages emerging from Bucharest was that defence auditing cannot be addressed by institutions working in isolation. The international conference provided a practical platform for managers and auditors to exchange experiences, methodologies and good practices in the fields of financial, performance and defence-related auditing.
Representatives of the European Court of Auditors, the OECD, the INTOSAI Development Initiative and national audit institutions contributed to the discussions.
Although national and international audit bodies operate under different mandates and legal frameworks, they face many common challenges. International cooperation between audit institutions, and sharing methodologies and lessons learned can contribute to stronger audit practices and more effective public oversight.
For IBAN, this international dialogue is not an additional activity alongside its audit mandate. It is part of the way in which the organisation seeks to strengthen professional standards and mutual understanding.
The same philosophy is reflected in IBAN’s growing engagement with SAIs across the NATO and wider European audit community. In 2026, IBAN has continued to develop professional cooperation arrangements with national audit institutions, creating opportunities for exchanges of experience, professional dialogue and mutual support. IBAN believes that public audit becomes stronger when auditors share experience while preserving the independence of their respective mandates.
Independence Does Not Mean Isolation
In September 2026, IBAN hosted the first meeting dedicated to dialogue between the Alliance’s external and internal audit communities. The meeting brought together IBAN and NATO’s Internal Oversight Service to exchange information on roles, responsibilities and professional practices. Although there is a clear distinction between internal and external audit functions, independence should not mean isolation, IBAN utilized this meeting to promote appropriate communication and coordination can help avoid unnecessary duplication, facilitate the exchange of relevant information and strengthen the overall audit and oversight framework, while fully preserving the respective mandates and independence of the two functions. In complex public-sector environments, the question is increasingly not simply whether institutions audit, but how different parts of the public audit ecosystem can exchange knowledge while preserving institutional independence.
A Shared Responsibility for the Audit Community
Ultimately, the role of public auditors in the defense and security sector is to provide oversight in areas where public interest is exceptionally high and where the consequences of ineffective management can extend well beyond financial considerations.
Taxpayers need confidence that public resources are properly managed. Governments need reliable assurance on the use of common funds. Decision-makers need objective information when addressing complex programmes. And citizens need to know that institutions entrusted with public resources are subject to effective and independent oversight.
The discussions in Bucharest demonstrated the value of bringing together auditors who operate in different institutional, national and professional environments but face increasingly similar challenges in this oversight function. The audit community can work together to continue developing the professional tools, international dialogue and institutional relationships necessary to overcome these challenges.
For the international audit community, this cooperation matters, and IBAN continues to pursue a natural part of its mission to maintain and develop relationships with the Supreme Audit Institutions of NATO member countries and with the wider public sector audit and INTOSAI community.
Bucharest was one step in that direction, and the message from the conference was clear: protecting security and strengthening accountability are not competing objectives. They are mutually reinforcing foundations of public trust.
| IBAN at a glance Established: 1953 Mandate: Independent external audit of NATO Member countries served: 32 NATO Allies Governance: Six Board members appointed by the North Atlantic Council Term: Four years, non-renewable Main audit areas: Financial audit, performance audit and NATO Security Investment Programme (NSIP) audit Accountability: North Atlantic Council Core principle: Independent assurance in support of transparency, accountability and sound governance |